Refresh Your Home For Fall
Buy New
To see product details, add this item to your cart.
Ships from: Amazon.com
Sold by: Amazon.com
To see product details, add this item to your cart. You can always remove it later.
Shipper / Seller
Amazon.com
Amazon.com
Shipper / Seller
Amazon.com
Returns
30-day refund / replacement
This item can be returned in its original condition for a full refund or replacement within 30 days of receipt.
Read full return policy
Payment
Secure transaction
Your transaction is secure
We work hard to protect your security and privacy. Our payment security system encrypts your information during transmission. We don’t share your credit card details with third-party sellers, and we don’t sell your information to others. Learn more
Gift options
Available at checkout
Available at checkout This item is a gift. Change
At checkout, you can add a custom message, a gift receipt for easy returns and have the item gift-wrapped
To see product details, add this item to your cart. You can always remove it later.
Unread book in perfect condition. Unread book in perfect condition. See less
Access codes and supplements are not guaranteed with used items.
Ships from and sold by SuperBookDeals---.
Added to

Sorry, there was a problem.

There was an error retrieving your Wish Lists. Please try again.

Sorry, there was a problem.

List unavailable.
Kindle app logo image

Download the free Kindle app and start reading Kindle books instantly on your smartphone, tablet, or computer - no Kindle device required.

Read instantly on your browser with Kindle for Web.

Using your mobile phone camera - scan the code below and download the Kindle app.

QR code to download the Kindle App

  • Reinforcement Learning for Finance: A Python-Based Introduction

Follow the author

Get new release updates & improved recommendations
Something went wrong. Please try your request again later.

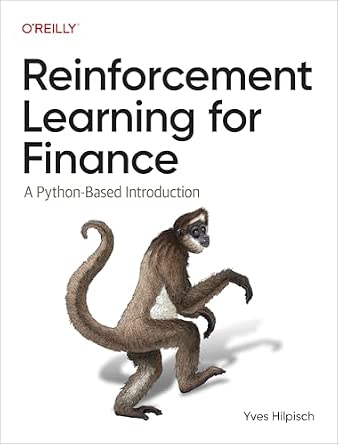
Reinforcement Learning for Finance: A Python-Based Introduction

5.0 out of 5 stars (4)

Purchase options and add-ons

Reinforcement learning (RL) has led to several breakthroughs in AI. The use of the Q-learning (DQL) algorithm alone has helped people develop agents that play arcade games and board games at a superhuman level. More recently, RL, DQL, and similar methods have gained popularity in publications related to financial research.

This book is among the first to explore the use of reinforcement learning methods in finance.

Author Yves Hilpisch, founder and CEO of The Python Quants, provides the background you need in concise fashion. ML practitioners, financial traders, portfolio managers, strategists, and analysts will focus on the implementation of these algorithms in the form of self-contained Python code and the application to important financial problems.

This book covers:

  • Reinforcement learning
  • Deep Q-learning
  • Python implementations of these algorithms
  • How to apply the algorithms to financial problems such as algorithmic trading, dynamic hedging, and dynamic asset allocation

    This book is the ideal reference on this topic. You'll read it once, change the examples according to your needs or ideas, and refer to it whenever you work with RL for finance.

    Dr. Yves Hilpisch is founder and CEO of The Python Quants, a group that focuses on the use of open source technologies for financial data science, AI, asset management, algorithmic trading, and computational finance.

Books with Buzz
Discover the latest buzz-worthy books, from mysteries and romance to humor and nonfiction. Explore more

Frequently bought together
This item: Reinforcement Learning for Finance: A Python-Based Introduction
$51.98
Get it as soon as Sunday, Sep 20
Only 12 left in stock (more on the way).
Ships from and sold by Amazon.com.
+
$40.49
Get it as soon as Sunday, Sep 20
Only 15 left in stock (more on the way).
Ships from and sold by Amazon.com.
+
$50.67
Get it as soon as Sunday, Sep 20
Only 10 left in stock (more on the way).
Ships from and sold by Amazon.com.
Total price: $00
To see our price, add these items to your cart.
Details
Added to Cart
Some of these items ship sooner than the others.
Choose items to buy together.

Customers also bought or read

Loading...

From the brand


From the Publisher

From the Preface

Reinforcement learning (RL) has enabled a number of breakthroughs in AI. One of the key algorithms in RL is deep Q-learning (DQL) that can be applied to a large number of dynamic decision problems. Popular examples are arcade games and board games, such as Go, in which RL and DQL algorithms have achieved superhuman performance in many instances. This has often happened despite the belief of experts that such feats would be impossible for decades to come.

Finance is a discipline with a strong connection between theory and practice. Theoretical advancements often find their way quickly into the applied domain. Many problems in finance are dynamic decision problems, such as the optimal allocation of assets over time. Therefore it is, on the one hand, theoretically interesting to apply DQL to financial problems. On the other hand, it is also in general quite easy and straightforward to apply such algorithms—usually after some thorough testing—in the financial markets.

In recent years, financial research has seen a strong growth in publications related to RL, DQL, and related methods applied to finance. However, there is hardly any resource in book form—beyond the purely theoretical ones—for those who are looking for an applied introduction to this exciting field. This book closes the gap in that it provides the required background in a concise fashion and otherwise focuses on the implementation of the algorithms in the form of self-contained Python code and the application to important financial problems.

Reinforcement Learning for Finance: A Python-Based Introduction

Target Audience

This book is intended as a concise, Python-based introduction to the major ideas and elements of RL and DQL as applied to finance. It should be useful to both students and academics as well as to practitioners in search of alternatives to existing financial theories and algorithms. The book expects basic knowledge of the Python programming language, object-oriented programming, and the major Python packages used in data science and machine learning, such as NumPy, pandas, matplotlib, scikit-learn, and TensorFlow.

Financial Theory with Python: A Gentle Introduction
Python for Finance: Mastering Data-Driven Finance
Python for Algorithmic Trading: From Idea to Cloud Deployment
Artificial Intelligence in Finance: A Python-Based Guide
Reinforcement Learning for Finance: A Python-Based Introduction
Customer Reviews
4.3 out of 5 stars 38
4.6 out of 5 stars 323
4.4 out of 5 stars 151
4.5 out of 5 stars 66
5.0 out of 5 stars 4
Also by Yves Hilpisch A Gentle Introduction Mastering Data-Driven Finance From Idea to Cloud Deployment A Python-Based Guide A Python-Based Introduction

Editorial Reviews

About the Author

Dr. Yves J. Hilpisch is the founder and CEO of The Python Quants (http://home.tpq.io), a group focusing on the use of open source technologies for financial data science, artificial intelligence, algorithmic trading, and computational finance. He is also the founder and CEO of The AI Machine (http://aimachine.io), a company focused on AI-powered algorithmic trading based on a proprietary strategy execution platform. Yves has a Diploma in Business Administration, a Ph.D. in Mathematical Finance, and is Adjunct Professor for Computational Finance. He lectures on computational finance, machine learning, and algorithmic trading at the CQF Program. Yves is the originator of the financial analytics library DX Analytics and organizes Meetup group events, conferences, and bootcamps about Python, artificial intelligence, and algorithmic trading in London, New York (http://aifat.tpq.io), Frankfurt, Berlin, and Paris. He has given keynote speeches at technology conferences in the United States, Europe, and Asia.

Product details

  • Publisher ‏ : ‎ O'Reilly Media
  • Publication date ‏ : ‎ November 19, 2024
  • Edition ‏ : ‎ 1st
  • Language ‏ : ‎ English
  • Print length ‏ : ‎ 212 pages
  • ISBN-10 ‏ : ‎ 109816914X
  • ISBN-13 ‏ : ‎ 978-1098169145
  • Item Weight ‏ : ‎ 13.6 ounces
  • Dimensions ‏ : ‎ 7 x 0.45 x 9.19 inches
  • Best Sellers Rank: #1,238,196 in Books (See Top 100 in Books)
  • Customer Reviews:
    5.0 out of 5 stars (4)

About the author

Follow authors to get new release updates, plus improved recommendations.
Yves J. Hilpisch
Brief content visible, double tap to read full content.
Full content visible, double tap to read brief content.

Dr. Yves J. Hilpisch is founder and CEO of The Python Quants (http://tpq.io), a group focusing on the use of open source technologies for financial data science, artificial intelligence, algorithmic trading, and computational finance. He is also the founder and CEO of The AI Machine (http://aimachine.io), a company focused on AI-powered algorithmic trading based on a proprietary strategy execution platform.

Yves has a Diploma in Business Administration, a Ph.D. in Mathematical Finance and is Adjunct Professor for Computational Finance.

Yves is the author of five books (https://home.tpq.io/books):

* Artificial Intelligence in Finance (O’Reilly, forthcoming)

* Python for Algorithmic Trading (O’Reilly, forthcoming)

* Python for Finance (2018, 2nd ed., O’Reilly)

* Listed Volatility and Variance Derivatives (2017, Wiley Finance)

* Derivatives Analytics with Python (2015, Wiley Finance)

Yves is the director of the first online training program leading to University Certificates in Python for Algorithmic Trading (https://home.tpq.io/certificates/pyalgo) and Computational Finance (https://home.tpq.io/certificates/compfin). He also lectures on computational finance, machine learning, and algorithmic trading at the CQF Program (http://cqf.com).

Yves is the originator of the financial analytics library DX Analytics (http://dx-analytics.com) and organizes Meetup group events, conferences, and bootcamps about Python, artificial intelligence and algorithmic trading in London (http://pqf.tpq.io), New York (http://aifat.tpq.io), Frankfurt, Berlin, and Paris. He has given keynote speeches at technology conferences in the United States, Europe, and Asia.