Buy New
-
To see product details, add this item to your cart.
Ships from: Amazon Sold by: itemspopularsonlineaindemand
Used - Good
-
To see product details, add this item to your cart.
Ships from: World of Books (previously glenthebookseller) Sold by: World of Books (previously glenthebookseller)
Download the free Kindle app and start reading Kindle books instantly on your smartphone, tablet, or computer - no Kindle device required.
Read instantly on your browser with Kindle for Web.
Using your mobile phone camera - scan the code below and download the Kindle app.
Follow the author
OK
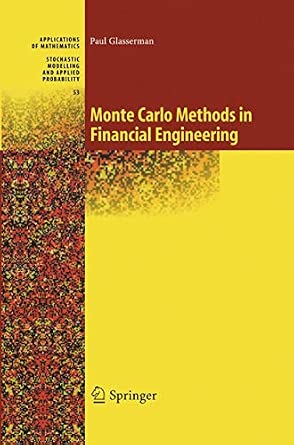
Monte Carlo Methods in Financial Engineering (Stochastic Modelling and Applied Probability, 53)
Purchase options and add-ons
Monte Carlo simulation has become an essential tool in the pricing of derivative securities and in risk management. These applications have, in turn, stimulated research into new Monte Carlo methods and renewed interest in some older techniques.
This book develops the use of Monte Carlo methods in finance and it also uses simulation as a vehicle for presenting models and ideas from financial engineering. It divides roughly into three parts. The first part develops the fundamentals of Monte Carlo methods, the foundations of derivatives pricing, and the implementation of several of the most important models used in financial engineering. The next part describes techniques for improving simulation accuracy and efficiency. The final third of the book addresses special topics: estimating price sensitivities, valuing American options, and measuring market risk and credit risk in financial portfolios.
The most important prerequisite is familiarity with the mathematical tools used to specify and analyze continuous-time models in finance, in particular the key ideas of stochastic calculus. Prior exposure to the basic principles of option pricing is useful but not essential.
The book is aimed at graduate students in financial engineering, researchers in Monte Carlo simulation, and practitioners implementing models in industry.
Mathematical Reviews, 2004: "... this book is very comprehensive, up-to-date and useful tool for those who are interested in implementing Monte Carlo methods in a financial context."
- ISBN-100387004513
- ISBN-13978-0387004518
- Edition2003rd
- PublisherSpringer
- Publication dateAugust 7, 2003
- LanguageEnglish
- Dimensions6.4 x 1.73 x 9.58 inches
- Print length609 pages
Discover the latest buzz-worthy books, from mysteries and romance to humor and nonfiction. Explore more
Frequently bought together

Customers who viewed this item also viewed
- Stochastic Calculus for Finance I: The Binomial Asset Pricing Model (Springer Finance)PaperbackFREE Shipping by AmazonGet it as soon as Monday, Sep 21Only 2 left in stock - order soon.
- Stochastic Calculus for Finance II: Continuous-Time Models (Springer Finance)HardcoverFREE Shipping by AmazonGet it as soon as Sunday, Sep 20Only 10 left in stock - order soon.
- Machine Learning in Finance: From Theory to PracticeHardcoverFREE Shipping by AmazonGet it as soon as Sunday, Sep 20
- Quantitative Risk Management: Concepts, Techniques and Tools - Revised Edition (Princeton Series in Finance)HardcoverFREE Shipping by AmazonGet it as soon as Tuesday, Sep 22Only 3 left in stock (more on the way).
- Monte Carlo Statistical Methods (Springer Texts in Statistics)PaperbackFREE Shipping by AmazonGet it as soon as Sunday, Sep 20Only 3 left in stock - order soon.
- Options, Futures, and Other Derivatives, Global EditionPaperbackFREE Shipping by AmazonGet it as soon as Sunday, Sep 20Only 3 left in stock - order soon.
Customers also bought or read
- Stochastic Calculus for Finance II: Continuous-Time Models (Springer Finance)
Hardcover$43.51$43.51FREE delivery Sun, Sep 20 - Stochastic Calculus for Finance I: The Binomial Asset Pricing Model (Springer Finance)
Paperback$45.65$45.65FREE delivery Mon, Sep 21 - Stochastic Differential Equations: An Introduction with Applications (Universitext)
Paperback$42.04$42.04FREE delivery Mon, Sep 21 - Analysis of Financial Time Series (Wiley Series in Probability and Statistics)
Hardcover$83.28$83.28FREE delivery Tue, Sep 22 - Quantitative Risk Management: Concepts, Techniques and Tools - Revised Edition (Princeton Series in Finance)
Hardcover$66.41$66.41FREE delivery Tue, Sep 22 - Quantitative Portfolio Management: The Art and Science of Statistical Arbitrage
Hardcover$33.94$33.94Delivery Sun, Sep 20 - Quantitative Trading: How to Build Your Own Algorithmic Trading Business (Wiley Trading)
Hardcover$34.44$34.44Delivery Mon, Sep 21 - The Elements of Quantitative Investing (Wiley Finance)
Hardcover$46.20$46.20FREE delivery Sun, Sep 20 - The Elements of Statistical Learning: Data Mining, Inference, and Prediction, Second Edition
Hardcover$71.59$71.59FREE delivery Mon, Sep 21 - Machine Learning for Asset Managers (Elements in Quantitative Finance)
Paperback$23.00$23.00Delivery Mon, Sep 21 - Introduction To Stochastic Calculus With Applications (3Rd Edition)
Paperback$28.67$28.67Delivery Mon, Sep 21 - Algorithmic and High-Frequency Trading (Mathematics, Finance and Risk)
Hardcover$82.37$82.37FREE delivery Sun, Sep 20 - The Volatility Surface: A Practitioner's Guide (Wiley Finance)
Hardcover$45.12$45.12FREE delivery Sep 28 - Oct 2 - Expected Returns: An Investor's Guide to Harvesting Market Rewards (The Wiley Finance Series)
Hardcover$50.49$50.49FREE delivery Mon, Sep 21 - Arbitrage Theory in Continuous Time (Oxford Finance Series)
Hardcover$41.27$41.27FREE delivery Mon, Sep 21 - Brownian Motion and Stochastic Calculus (Graduate Texts in Mathematics, 113)
Paperback$32.47$32.47Delivery Mon, Sep 21 - Option Volatility and Pricing: Advanced Trading Strategies and Techniques, 2nd Edition
Hardcover$91.83$91.83FREE delivery Sun, Sep 20 - Options, Futures, and Other Derivatives, Global Edition
Paperback$52.53$52.53FREE delivery Sun, Sep 20 - Probability with Martingales (Cambridge Mathematical Textbooks)
Paperback$39.88$39.88FREE delivery Sun, Sep 20 - Algorithmic Trading: Winning Strategies and Their Rationale (Wiley Trading)
Hardcover$49.29$49.29FREE delivery Sep 22 - 25 - An Introduction to Statistical Learning: with Applications in Python (Springer Texts in Statistics)
Hardcover$56.21$56.21FREE delivery Fri, Oct 2 - The xVA Challenge: Counterparty Risk, Funding, Collateral, Capital and Initial Margin (Wiley Finance)
Hardcover$45.63$45.63FREE delivery Sun, Sep 20 - Trades, Quotes and Prices: Financial Markets Under the Microscope
Hardcover$91.38$91.38FREE delivery Sun, Sep 20
Editorial Reviews
Review
"Paul Glasserman has written an astonishingly good book that bridges financial engineering and the Monte Carlo method. The book will appeal to graduate students, researchers, and most of all, practicing financial engineers … You will want to have prior knowledge of both the Monte Carlo method and financial engineering. If you do, you will find the book to be a goldmine … So often, financial engineering texts are very theoretical. This book is not. The Monte Carlo method serves as a unifying theme that motivates practical discussions of how to implement real models on real trading floors. You will learn plenty of financial engineering amidst these pages. The writing is a pleasure to read. Topics are timely and relevant. Glasserman's is a must-have book for financial engineers." -Glyn Holton, Contingency AnalysisMathematical Reviews, 2004: "... this book is very comprehensive, up-to-date and useful tool for those who are interested in implementing Monte Carlo methods in a financial context."
From the reviews:
"This recent book is a valuable addition to the references devoted to Monte Carlo methods. … the author succeeded in choosing the most actual topics in financial engineering and in presenting them in an appropriate way by keeping a suitable balance between mathematical rigour and an audience friendly language. … To help the reader, three appendices provide basic results on convergence concepts … . A large bibliography of 358 entries accompanies this text. In short, the reader will find this book extremely lucid and useful." (Radu Theodorescu, Zentralblatt MATH, Vol. 1038 (13), 2004)
"To keep it short, let me summarize the recension in one phrase: Paul Glausserman’s book is a ‘strong buy’ for everybody in the financial community. … one gets 596 pages full of valuable information on all aspects of Monte Carlo simulation. … Altogether, I can encourage everyone interested in Monte Carlo methodsin finance to read the book. It is very well written … comes with a carefully selected bibliography (358 references) and a helpful index, thus making it really worth the buy." (Ralf Werner, OR – Spectrum Operations Research Spectrum, Issue 27, 2005)
"Glasserman’s new book is a remarkable presentation of the current state of the art of Monte Carlo Methods in Financial Engineering. … lot of material which is sometimes hard to access has been composed into one volume. … a high quality monograph which is both suitable as a reference for practitioners and researchers as well as a textbook … . The list of references is by itself a valuable aspect. The refreshing writing style of the author is tailor-made for the thirsty reader … ." (Uwe Wystup, www.mathfinance.de, November, 2003)
"Paul Glasserman has written an astonishingly good book that bridges financial engineering and the Monte Carlo method. The book will appeal to graduate students, researchers, and most of all, practicing financial engineers. It is an advanced book. … The presentation is masterful. … You will learn plenty of financial engineering amidst the pages. The writing is a pleasure to read. Topics are timely and relevant. Glasserman’s is a must-have book for financial engineers." (www.riskbook.com, Dezember, 2003)
"This book is divided into three parts. … the aim of the author is … to give a precise description of the different techniques in order to facilitate their implementation. In my opinion, this book is a very comprehensive, up-to-date and useful tool for those who are interested in implementing Monte Carlo methods in a financial context." (Benjamin Jourdain, Mathematical Reviews, 2004g)
"The publication of this book is an important event in computational finance. For many years, Monte Carlo methods have been successfully applied to solve diverse problems in financial mathematics. By publishing this book the author deserves much credit for avery good attempt to lift such applications to a new level. … the book may well become a major reference in the field of applications of Monte Carlo methods in financial engineering. This is because the book is well structured and well written … ." (A Zhigljavsky, Journal of the Operational Research Society, Vol. 57, 2006)
From the Back Cover
Monte Carlo simulation has become an essential tool in the pricing of derivative securities and in risk management. These applications have, in turn, stimulated research into new Monte Carlo methods and renewed interest in some older techniques.
This book develops the use of Monte Carlo methods in finance and it also uses simulation as a vehicle for presenting models and ideas from financial engineering. It divides roughly into three parts. The first part develops the fundamentals of Monte Carlo methods, the foundations of derivatives pricing, and the implementation of several of the most important models used in financial engineering. The next part describes techniques for improving simulation accuracy and efficiency. The final third of the book addresses special topics: estimating price sensitivities, valuing American options, and measuring market risk and credit risk in financial portfolios.
The most important prerequisite is familiarity with the mathematical tools used to specify and analyze continuous-time models in finance, in particular the key ideas of stochastic calculus. Prior exposure to the basic principles of option pricing is useful but not essential.
The book is aimed at graduate students in financial engineering, researchers in Monte Carlo simulation, and practitioners implementing models in industry.
Product details
- Publisher : Springer
- Publication date : August 7, 2003
- Edition : 2003rd
- Language : English
- Print length : 609 pages
- ISBN-10 : 0387004513
- ISBN-13 : 978-0387004518
- Item Weight : 2.35 pounds
- Dimensions : 6.4 x 1.73 x 9.58 inches
- Part of series : Stochastic Modelling and Applied Probability
- Best Sellers Rank: #232,115 in Books (See Top 100 in Books)
- #27 in Econometrics & Statistics
- #27 in Economic Theory (Books)
- #29 in Public Finance (Books)
- Customer Reviews:
About the author

Discover more of the author’s books, see similar authors, read book recommendations and more.