Buy New
-
To see product details, add this item to your cart.
Ships from: Amazon.com Sold by: Amazon.com
Buy New
-
To see product details, add this item to your cart.
Ships from: Amazon.com
Sold by: Amazon.com
Used - Very Good
-
To see product details, add this item to your cart.
Ships from: books_from_california Sold by: books_from_california
Used - Very Good
-
To see product details, add this item to your cart.
Ships from: books_from_california
Sold by: books_from_california
Download the free Kindle app and start reading Kindle books instantly on your smartphone, tablet, or computer - no Kindle device required.
Read instantly on your browser with Kindle for Web.
Using your mobile phone camera - scan the code below and download the Kindle app.
Follow the author
Get new release updates & improved recommendations
Something went wrong. Please try your request again later.
OK
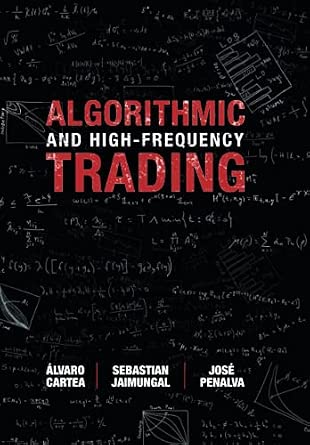
Algorithmic and High-Frequency Trading (Mathematics, Finance and Risk)
by
Álvaro Cartea
(Author),
Sebastian Jaimungal
(Author),
José Penalva
(Author)
&
0
more Format: Hardcover
Sorry, there was a problem loading this page. Try again.
Purchase options and add-ons
The design of trading algorithms requires sophisticated mathematical models backed up by reliable data. In this textbook, the authors develop models for algorithmic trading in contexts such as executing large orders, market making, targeting VWAP and other schedules, trading pairs or collection of assets, and executing in dark pools. These models are grounded on how the exchanges work, whether the algorithm is trading with better informed traders (adverse selection), and the type of information available to market participants at both ultra-high and low frequency. Algorithmic and High-Frequency Trading is the first book that combines sophisticated mathematical modelling, empirical facts and financial economics, taking the reader from basic ideas to cutting-edge research and practice. If you need to understand how modern electronic markets operate, what information provides a trading edge, and how other market participants may affect the profitability of the algorithms, then this is the book for you.
- ISBN-109781107091146
- ISBN-13978-1107091146
- Edition1st
- PublisherCambridge University Press
- Publication dateAugust 6, 2015
- LanguageEnglish
- Dimensions6.69 x 0.85 x 9.61 inches
- Print length356 pages
Books with Buzz
Discover the latest buzz-worthy books, from mysteries and romance to humor and nonfiction. Explore more
Frequently bought together
This item: Algorithmic and High-Frequency Trading (Mathematics, Finance and Risk)
$82.37$82.37
Get it as soon as Sunday, Sep 20
In Stock
$91.38$91.38
Get it as soon as Sunday, Sep 20
Only 5 left in stock - order soon.
$105.00$105.00
Get it as soon as Sunday, Sep 20
Only 3 left in stock (more on the way).
Total price: $00$00
To see our price, add these items to your cart.
Try again!
Added to Cart
Some of these items ship sooner than the others.
Choose items to buy together.
Customers who viewed this item also viewed
Page 1 of 1 Start over
- Trading and Exchanges: Market Microstructure for PractitionersHardcoverFREE Shipping by AmazonGet it as soon as Sunday, Sep 20Only 3 left in stock (more on the way).
- Trades, Quotes and Prices: Financial Markets Under the MicroscopeHardcoverFREE Shipping by AmazonGet it as soon as Sunday, Sep 20Only 5 left in stock - order soon.
- Advances in Financial Machine LearningHardcoverFREE Shipping on orders over $35 shipped by AmazonGet it as soon as Sunday, Sep 20
- Market Microstructure TheoryPaperbackFREE Shipping on orders over $35 shipped by AmazonGet it as soon as Monday, Sep 21
- High-Frequency Trading: A Practical Guide to Algorithmic Strategies and Trading Systems (Wiley Trading)HardcoverFREE Shipping by AmazonGet it as soon as Sunday, Sep 27Usually ships within 7 days
- The Financial Mathematics of Market Liquidity (Chapman and Hall/CRC Financial Mathematics Series)Olivier GueantHardcoverFREE Shipping by AmazonGet it as soon as Sunday, Sep 20Only 8 left in stock - order soon.
Customers also bought or read
Page 1 of 1Start over
- Trades, Quotes and Prices: Financial Markets Under the Microscope
Hardcover$91.38$91.38FREE delivery Sun, Sep 20 - Trading and Exchanges: Market Microstructure for Practitioners
Hardcover$105.00$105.00FREE delivery Sun, Sep 20 - Quantitative Portfolio Management: The Art and Science of Statistical Arbitrage
Hardcover$33.94$33.94Delivery Sun, Sep 20 - High-Frequency Trading: A Practical Guide to Algorithmic Strategies and Trading Systems (Wiley Trading)
Hardcover$44.14$44.14FREE delivery Sep 27 - 28 - Analysis of Financial Time Series (Wiley Series in Probability and Statistics)
Hardcover$83.28$83.28FREE delivery Tue, Sep 22 - The Elements of Quantitative Investing (Wiley Finance)
Hardcover$46.20$46.20FREE delivery Sun, Sep 20 - Empirical Market Microstructure: The Institutions, Economics, and Econometrics of Securities Trading
Hardcover$110.00$110.00FREE delivery Sun, Sep 20 - The Financial Mathematics of Market Liquidity (Chapman and Hall/CRC Financial Mathematics Series)
Hardcover$73.65$73.65FREE delivery Sun, Sep 20 - Machine Learning for Algorithmic Trading: Predictive models to extract signals from market and alternative data for systematic trading strategies with Python
Paperback$47.60$47.60FREE delivery Mon, Sep 21 - Option Volatility and Pricing: Advanced Trading Strategies and Techniques, 2nd Edition
Hardcover$90.14$90.14FREE delivery Sun, Sep 20 - Algorithmic Trading: Winning Strategies and Their Rationale (Wiley Trading)
Hardcover$49.29$49.29FREE delivery Sep 22 - 25 - Algorithmic Trading and DMA: An introduction to direct access trading strategies
Paperback$45.58$45.58FREE delivery Sep 30 - Oct 2 - Quantitative Trading: How to Build Your Own Algorithmic Trading Business (Wiley Trading)
Hardcover$34.44$34.44Delivery Mon, Sep 21 - Options, Futures, and Other Derivatives, Global Edition
Paperback$52.53$52.53FREE delivery Sun, Sep 20 - Machine Learning for Asset Managers (Elements in Quantitative Finance)
Paperback$23.00$23.00Delivery Mon, Sep 21 - The Volatility Surface: A Practitioner's Guide (Wiley Finance)
Hardcover$45.12$45.12FREE delivery Sep 27 - Oct 1 - Advanced Portfolio Management: A Quant's Guide for Fundamental Investors
Hardcover$22.26$22.26Delivery Sun, Sep 20 - Inside the Black Box: A Simple Guide to Systematic Investing (Wiley Finance)
Hardcover$28.54$28.54Delivery Sun, Sep 20 - Algorithmic Trading Methods: Applications Using Advanced Statistics, Optimization, and Machine Learning Techniques
Paperback$62.69$62.69FREE delivery Sun, Sep 20 - Systematic Trading: A unique new method for designing trading and investing systems
Hardcover$48.49$48.49FREE delivery Sun, Sep 20 - The Man Who Solved the Market: How Jim Simons Launched the Quant Revolution
Hardcover$13.76$13.76Delivery Sep 29 - Oct 1 - The Laws of Trading: A Trader's Guide to Better Decision-Making for Everyone (Wiley Trading)
Hardcover$20.27$20.27Delivery Sun, Sep 20 - Expected Returns: An Investor's Guide to Harvesting Market Rewards (The Wiley Finance Series)
Hardcover$50.49$50.49FREE delivery Mon, Sep 21 - Heard on The Street: Quantitative Questions from Wall Street Job Interviews
Paperback$45.00$45.00FREE delivery Sep 21 - 24 - Monte Carlo Methods in Financial Engineering (Stochastic Modelling and Applied Probability, 53)
Hardcover$53.17$53.17FREE delivery Tue, Sep 22
Loading...
Editorial Reviews
Review
"[This book] is an important and timely textbook on algorithmic trading. Human traders in financial markets are an endangered species, gradually replaced by computers and algorithms. In this new world, designing and coding trading strategies requires knowledge of market microstructure, basic economic principles governing price formation in financial markets, and stylized facts about price dynamics and trading activity. It also requires specific mathematical tools, such as stochastic control, and understanding of how these tools are used to solve trading problems. Algorithmic and High-Frequency Trading is unique in that it provides a unified treatment of these topics. I enjoyed reading it and recommend it highly to students or practitioners interested in mathematical models used in algorithmic trading."
Thierry Foucault, HEC Paris
"This book is the first to give a thorough coverage of optimal strategies in algorithmic and high-frequency trading, from the very modern point of view of dynamic stochastic optimization and based on cutting-edge work, much of which is by these authors. Other books cover the mechanics and statistics of high-frequency market dynamics, but none covers the mathematical aspects to this depth. It would be a great textbook for a graduate course in optimal trading."
Robert Almgren, Quantitative Brokers
"This textbook is a welcome addition to the literature on algorithmic trading and the high-frequency markets. It fills a significant gap by bringing cutting-edge mathematical models to bear on the analysis and implementation of practical algorithms. Using a unique blend of microstructure theory, financial data analysis, and mathematical models, the authors walk the reader through the maze of the high-frequency markets, detailing how the exchanges work, and what kind of data they generate. Trading algorithms and their practical implementations are described in easy-to-understand prose, and illustrated with enlightening simulations. This text is ideal for graduate students and researchers in financial mathematics and engineering, as well as for practitioners already working in the field."
René Carmona, Princeton University
Thierry Foucault, HEC Paris
"This book is the first to give a thorough coverage of optimal strategies in algorithmic and high-frequency trading, from the very modern point of view of dynamic stochastic optimization and based on cutting-edge work, much of which is by these authors. Other books cover the mechanics and statistics of high-frequency market dynamics, but none covers the mathematical aspects to this depth. It would be a great textbook for a graduate course in optimal trading."
Robert Almgren, Quantitative Brokers
"This textbook is a welcome addition to the literature on algorithmic trading and the high-frequency markets. It fills a significant gap by bringing cutting-edge mathematical models to bear on the analysis and implementation of practical algorithms. Using a unique blend of microstructure theory, financial data analysis, and mathematical models, the authors walk the reader through the maze of the high-frequency markets, detailing how the exchanges work, and what kind of data they generate. Trading algorithms and their practical implementations are described in easy-to-understand prose, and illustrated with enlightening simulations. This text is ideal for graduate students and researchers in financial mathematics and engineering, as well as for practitioners already working in the field."
René Carmona, Princeton University
Book Description
A straightforward guide to the mathematics of algorithmic trading that reflects cutting-edge research.
About the Author
Álvaro Cartea is a Reader in Financial Mathematics at University College London. Before joining UCL, he was Associate Professor of Finance at Universidad Carlos III, Madrid (2009–2012) and from 2002 to 2009 he was a Lecturer (with tenure) in the School of Economics, Mathematics and Statistics at Birkbeck, University of London. He was previously JP Morgan Lecturer in Financial Mathematics at Exeter College, Oxford.
Sebastian Jaimungal is an Associate Professor and Chair of Graduate Studies in the Department of Statistical Sciences, University of Toronto, where he teaches in the PhD and Masters in Mathematical Finance programs. He consults for major banks and hedge funds focusing on implementing advance derivative valuation engines and algorithmic trading strategies. He is also an associate editor for the SIAM Journal on Financial Mathematics, the International Journal of Theoretical and Applied Finance, the journal Risks and the Argo newsletter. Jaimungal is Vice Chair for the SIAM activity group on Financial Engineering and Mathematics, and his research has been widely published in academic and practitioner journals. His recent interests include high-frequency and algorithmic trading, applied stochastic control, mean-field games, real options, and commodity models and derivative pricing.
José Penalva is an Associate Professor at the Universidad Carlos III de Madrid, where he teaches in the PhD and Masters in Finance programs, as well as at the undergraduate level. He is currently working on information models and market microstructure and his research has been published in Econometrica and other top academic journals.
Sebastian Jaimungal is an Associate Professor and Chair of Graduate Studies in the Department of Statistical Sciences, University of Toronto, where he teaches in the PhD and Masters in Mathematical Finance programs. He consults for major banks and hedge funds focusing on implementing advance derivative valuation engines and algorithmic trading strategies. He is also an associate editor for the SIAM Journal on Financial Mathematics, the International Journal of Theoretical and Applied Finance, the journal Risks and the Argo newsletter. Jaimungal is Vice Chair for the SIAM activity group on Financial Engineering and Mathematics, and his research has been widely published in academic and practitioner journals. His recent interests include high-frequency and algorithmic trading, applied stochastic control, mean-field games, real options, and commodity models and derivative pricing.
José Penalva is an Associate Professor at the Universidad Carlos III de Madrid, where he teaches in the PhD and Masters in Finance programs, as well as at the undergraduate level. He is currently working on information models and market microstructure and his research has been published in Econometrica and other top academic journals.
Product details
- ASIN : 1107091144
- Publisher : Cambridge University Press
- Publication date : August 6, 2015
- Edition : 1st
- Language : English
- Print length : 356 pages
- ISBN-10 : 9781107091146
- ISBN-13 : 978-1107091146
- Item Weight : 1.92 pounds
- Dimensions : 6.69 x 0.85 x 9.61 inches
- Best Sellers Rank: #180,961 in Books (See Top 100 in Books)
- #16 in Financial Engineering (Books)
- #294 in Investment Analysis & Strategy
- #350 in Economics (Books)
- Customer Reviews:
About the author
Follow authors to get new release updates, plus improved recommendations.

Discover more of the author’s books, see similar authors, read book recommendations and more.


![The Candlestick Trading Bible [50 in 1]: Learn How to Read Price Action, Spot Profitable Setups, and Trade with Confidence Using the Most Effective Candlestick Patterns and Chart Strategies](https://m.media-amazon.com/images/I/51JozcNDI6L._AC_SR100,100_QL65_.jpg)